
Bond valuation is one of the most important practical uses of discounting. This guide covers how a bond’s present value is calculated from its two components, the coupon payments and the principal repayment, with a full worked example.
It then explains the bond market conventions that fill in missing information, how accrued interest separates a bond’s clean and dirty prices, and finally how and why changes in market interest rates move a bond’s value in the opposite direction.
How Bond Valuation Works
The present value of a bond is the sum of the present values of all the future cash flows it will pay out. In that sense, bond valuation sounds simple: find the future stream of payments due on the bond, find their present value, and that’s the bond’s value.
That’s true in theory. In practice, estimating a parameter like the discount rate can be very difficult, and different discount rates produce very different valuations. Bond valuation really comes down to forming a view on what the future discount rate will be.
The present value of a bond is calculated in two components:
- Annuity: Bonds make a series of coupon payments, which are periodic interest payments. In many markets, including the US, these are semi-annual, since paying interest twice a year is a widely followed bond market convention.
Bonds can have two different values: the face (par) value, which is the amount repaid at maturity, and the market value, which is its current trading price.
If the interest payment isn’t given directly, it has to be computed from the face value. Interest payments are always calculated using face value, never market value.
The annual interest rate is converted into a semi-annual (or otherwise appropriate) rate and plugged into the annuity formula, along with the other details, to find the present value of the coupon payments due.
- Lump sum: Bonds pay interest throughout their life but repay the principal only once, at the end. That principal is therefore a lump-sum payment that may need to be discounted many years into the future.
Even though this payment isn’t received twice a year like the coupons, the same semi-annual discount rate is still used to find its present value.
The final step is simply to add the present value of the annuity (the coupon payments) to the present value of the lump sum (the principal). That sum is the present value of the bond.
Worked Example
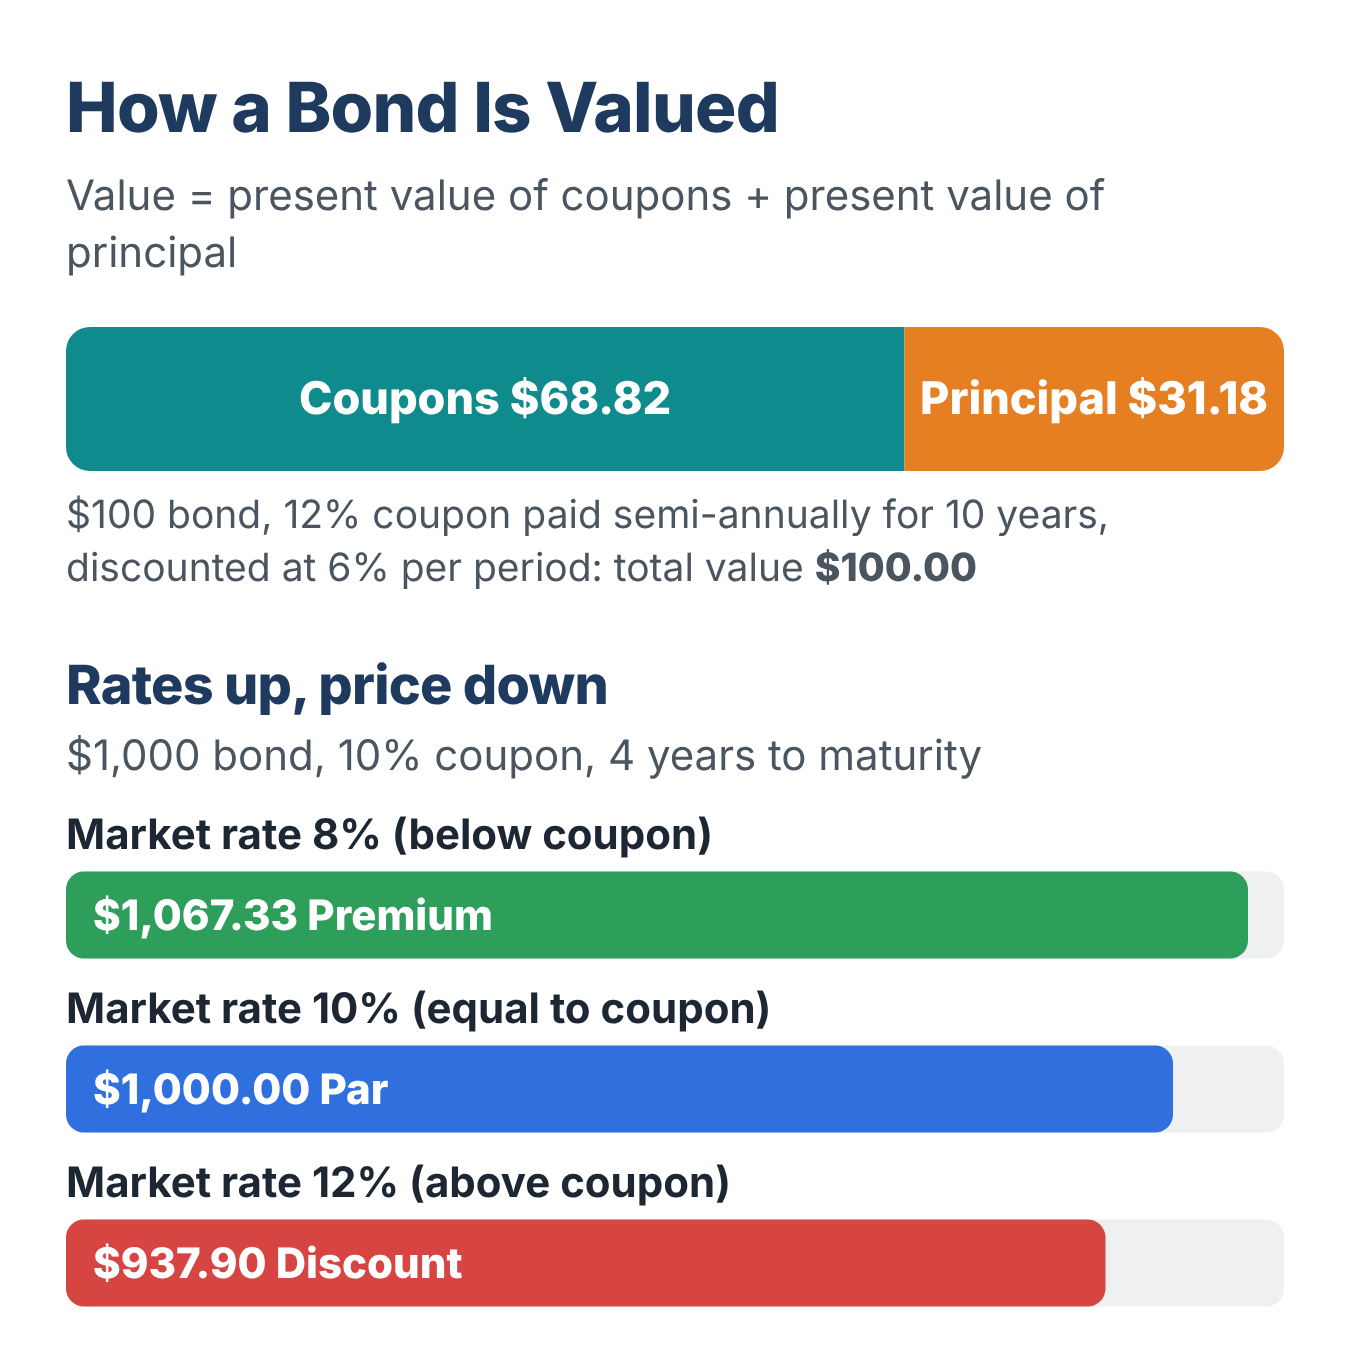
Consider a bond with a face value of $100. The interest rate is 12% on an annual basis, and the bond pays semi-annual interest for 10 years, after which the principal is repaid and the bond expires.
Present Value of Interest Payments:
- Number of periods = 20 (10 years, paid semi-annually)
- Discount rate = 6% per period (the 12% annual rate halved to match the semi-annual periods)
- Payment = $6 per period (6% of the $100 face value)
This gives a present value of the coupon payments of $68.82.
Present Value of Principal Due: The $100 principal is repaid after 20 periods at a 6% per-period discount rate, giving a present value of $31.18.
Adding the two components together ($68.82 + $31.18) gives a present value of $100 for the bond.
In this example, the bond’s value equals its face value because the discount rate used (6% per period, or 12% annually) exactly matches the bond’s own coupon rate. On a coupon date, a bond is always worth par when the market discount rate equals its coupon rate.
In real life, bond values swing based on expectations of what the future discount rate will be. It’s the expected future discount rate that drives bond values, not simply the current one.
| Component | What It Represents | How It’s Valued |
|---|---|---|
| Annuity | The bond’s periodic coupon (interest) payments | Present value of an annuity, using the coupon amount, number of periods, and per-period discount rate |
| Lump sum | The one-time repayment of the bond’s principal (face value) at maturity | Present value of a single future payment, discounted back over the full number of periods |
Bond Market Conventions: The Information That Goes Unsaid
Sometimes a bond problem seems to be missing information. The face value isn’t stated. The payment frequency isn’t mentioned. This is usually not an error.
The bond market treats certain details as understood, so they are rarely spelled out. These are called bond market conventions. Textbook questions, exam problems and real trade quotes all lean on them.
The golden rule: if a detail is stated explicitly, always use it. Use a convention only when the detail is missing.
Face Value Convention
If the face value is given, use it. If it isn’t, assume a face value of either $100 or $1,000.
You may state your choice as an assumption in your answer. But in the absence of data, the market convention already supports these two values.
Payment Frequency Convention
Check whether the frequency of interest payments is stated. If it is, use the rate that matches it.
If it isn’t, assume interest is paid semi-annually. This is the standard in the US and several other major bond markets, so it is a reasonable default. Some markets, including many European government bonds, pay annually, so check the market when it matters.
This choice has a large effect on the answer. Going from annual to semi-annual means halving the rate and doubling the number of periods, exactly as in the worked example above (12% a year becomes 6% for each of 20 periods).
Day Count Conventions
Day count conventions define how days are counted when calculating interest that has built up between payment dates. This is known as accrued interest.
Day counts are not uniform across the world. Each market has its own convention, and traders must know which one applies. They fall into a few broad types:
- 30/360: every month is treated as 30 days, and the year as 360 days, so a six-month coupon period always has 180 days.
- Actual/360: actual days elapsed, over a 360-day year.
- Actual/365: actual days elapsed, over a 365-day year.
- Actual/Actual: actual days elapsed, over the actual number of days in the period. For government bonds such as US Treasuries, the count is divided by the actual days in the current coupon period (anywhere from 181 to 184 days for a semi-annual bond).
30/360 itself comes in variants. The US version, used for US corporate bonds, and the European version (30E/360) differ mainly in how they treat a date that falls on the 31st of a month.
As a rough guide, 30/360 is common for corporate bonds in the US, Actual/Actual is used for US Treasury bonds and UK gilts, and Actual/360 is common in US dollar and euro money markets (sterling money markets use Actual/365). In India, government securities use 30/360.
Interest Payment Date Conventions
Another convention concerns when interest is actually paid. The dates depend on the specific bond.
Terms such as EOM (end of month) are part of this. Under an EOM rule, if a bond’s coupon falls on the last day of a month, later coupons also fall on the last day of their months. So a coupon paid on February 28 (the last day of the month in a non-leap year) would next be paid on August 31, not August 28.
Students of bond valuation should know these terms and how they affect valuation.
| Convention | Default If Not Stated | Why It Matters |
|---|---|---|
| Face value | $100 or $1,000 | Coupons are calculated on face value |
| Payment frequency | Semi-annual | Changes the rate per period and the number of periods |
| Day count | Depends on the market (for example 30/360) | Changes accrued interest between coupon dates |
| Payment dates | Set by the bond’s terms (for example EOM rules) | Affects when cash flows are received |
This list is not complete. Many more conventions apply, some across all markets and some in specific ones. The takeaway is simple: even when a detail is not written in the question, it may be implied by the market.
Clean Price vs. Dirty Price
The worked example above values a bond on a coupon date. Most trades, though, settle somewhere between two coupon dates. The seller has held the bond for part of the current period, but the buyer will receive the whole next coupon. The buyer therefore pays the seller the interest built up so far. This is where the day count convention comes into play.
Bond prices come in two forms:
- Dirty price (full or invoice price): the total cash the buyer actually pays at settlement. It is the present value of all the bond’s remaining cash flows, and it includes the accrued interest.
- Clean price (quoted price): the dirty price minus accrued interest. Dealers and trading screens usually quote this price, in the US, UK and India among other markets, because it does not jump up and down around each coupon date.
Accrued interest is the coupon multiplied by the share of the coupon period that has passed, counted under the bond’s day count convention. It runs up to the settlement date, not the trade date.
Example: Take a $1,000 bond with a 6% coupon, paying $30 every February 15 and August 15. A trade settles on May 1, 2026, at a quoted (clean) price of $985.00.
If it is a US corporate bond (30/360), the days from February 15 to May 1 count as 3 months of 30 days minus 14 days, or 76 days, out of a 180-day period. Accrued interest is $30 x 76/180 = $12.67, so the buyer pays a dirty price of $985.00 + $12.67 = $997.67.
If it is a US Treasury (Actual/Actual), the actual days from February 15 to May 1, 2026 are 75, and the actual coupon period from February 15 to August 15, 2026 is 181 days. Accrued interest is $30 x 75/181 = $12.43, and the dirty price is $997.43.
The same bond, quoted at the same clean price, costs 24 cents more under 30/360. On a large trade, that gap adds up. Always confirm whether a quote is clean or dirty, and which day count applies, before you settle.
How Changes in Interest Rates Affect Bond Value
Interest rates are one of the most important factors in determining bond value. Other inputs to a bond valuation, such as the payment amount and the number of periods, are fixed numbers that simply get plugged into the present value formula.
The discount rate is different: it is a matter of judgment. Each investor decides what return they require from the bond, so different investors arrive at different fair values for the same bond.
That’s exactly why some investors see a bond as undervalued while others see it as overvalued, and why trades happen at all.
The Inverse Relationship
Interest rates have an inverse relationship with bonds and fixed-income securities generally. A fall in interest rates increases a bond’s value, while a rise in interest rates decreases it.
In theory, this repricing happens once news of an interest rate change becomes public. In practice, markets price in expected changes ahead of time.
By the time a rate change is actually announced, much of the move is already reflected in the price and the remaining price change is relatively small. Markets trade on expectations about the future, not just on facts as they’re announced.
Example: Consider a bond with a face value of $1,000 and a coupon rate of 10% per annum. It pays semi-annual coupons for the next 4 years (8 periods, $50 per coupon). Its value under three different market interest rate scenarios:
- Market rate equal to the coupon rate (10%): The bond’s market value is $1,000. It trades exactly at par, since the discount rate matches its own coupon rate.
- Market rate above the coupon rate (12%): The bond’s market value falls to $937.90. As interest rates rose from 10% to 12%, the bond’s fixed 10% coupon became less attractive relative to what newly issued bonds now pay, so its price fell below par.
- Market rate below the coupon rate (8%): The bond’s market value rises to $1,067.33. As interest rates fell from 10% to 8%, the bond’s fixed 10% coupon became more attractive relative to newly issued bonds, so its price rose above par.
The Logic Behind the Inverse Relationship
The logic is straightforward. With a fixed-income security, the nominal (dollar) value of the coupon payments is locked in. The coupon payments stay the same no matter what happens to interest rates, because they’re fixed by the terms of the bond.
What changes is how attractive that fixed income is compared with the alternatives. When interest rates rise, investors have the option of putting their money into other bonds that now offer a higher yield. A bond still paying the old, lower coupon becomes relatively overpriced.
Its price has to fall until it’s fairly valued again relative to other bonds on a yield basis. The reverse happens when rates fall.
| Market Interest Rate | Relative to the 10% Coupon | Bond Value (on $1,000 face) | Trades At |
|---|---|---|---|
| 10% | Equal | $1,000.00 | Par |
| 12% | Above | $937.90 | Discount |
| 8% | Below | $1,067.33 | Premium |
Frequently Asked Questions
What are the two components of a bond’s present value?
The present value of the annuity of coupon payments due over the bond’s life, plus the present value of the lump-sum principal repayment at maturity. Adding the two gives the bond’s total present value.
Why does a bond trade at exactly its face value when the market rate equals the coupon rate?
Because the discount rate used to value the bond’s cash flows is the same rate the bond itself pays, the present value of those cash flows works out to exactly the face value on a coupon date. The bond trades at par.
Why do bond prices fall when interest rates rise?
A bond’s coupon payments are fixed, so when market interest rates rise, newly issued bonds offer a higher yield than the existing bond’s fixed coupon. To stay competitively priced, the existing bond’s market value has to fall.
Is it the current interest rate or the expected future interest rate that drives bond prices?
Expectations matter more. Markets tend to price in anticipated rate changes ahead of time, so the actual announcement usually moves prices less than the earlier shift in expectations did.
What are bond market conventions?
They are standard assumptions that the bond market treats as understood, such as the face value, the payment frequency and the day count method. They are used when these details are not stated.
What face value should I assume if a question doesn’t give one?
Assume $100 or $1,000. Either is consistent with market convention, and you can state your choice as an assumption.
Why is interest assumed to be semi-annual?
Because semi-annual coupons are the standard in the US and several other major bond markets. If the payment frequency is given, always use that instead.
Why do day count conventions matter?
They decide how much interest has built up between coupon dates, which sets the gap between a bond’s clean and dirty price. Different conventions give slightly different accrued interest, so traders must use the one that applies in their market.