
Governments everywhere face the same problem: the need for roads, airports, power plants, hospitals and water systems far exceeds the money available in public budgets. Public-private partnerships (PPPs) are one of the main tools used to close that gap.
In a PPP, a private company finances, builds and often operates a public asset for many years, under a long-term contract with the government. The government gets the asset sooner and benefits from private skills. The private partner earns a return for taking on agreed risks.
PPPs are not a magic solution. They work only when the economics are sound, the contract is well designed and both sides keep their promises over decades. Badly structured PPPs can cost taxpayers more than conventional public projects.
This article explains how PPP projects are selected, the economics behind them, how private partners are paid, how contracts adjust over time, what happens if a contract ends early, and whether governments should take equity stakes.
What Is a Public-Private Partnership?
A public-private partnership is an arrangement in which a government and a private entity work together to finance, build, operate or maintain infrastructure. It sits between full government ownership and outright privatization: the state keeps regulatory oversight, while the private party brings capital, expertise and operational efficiency.
PPPs are usually structured through a special purpose vehicle (SPV), a legally independent company created only for the project. The SPV holds the private equity and any government contributions, such as land or concession rights. This ring-fences the project’s finances and makes clear to lenders, investors and regulators who is responsible for what.
| PPP Model | What the Private Partner Does | Who Owns the Asset |
|---|---|---|
| Build-Operate-Transfer (BOT) | Builds and operates, collecting fees, then hands over | Government at the end of the term |
| Build-Own-Operate-Transfer (BOOT) | Builds, owns and operates for a period, then transfers | Private, then government |
| Build-Own-Operate (BOO) | Builds, owns and operates indefinitely | Private partner |
| Design-Build-Finance-Operate (DBFO) | Designs, builds, finances and runs the asset, often paid by the government | Usually government |
| Hybrid annuity (India) | Builds roads; government pays 40% of the cost during construction and the remaining 60% as annuities over the operating period | Government |
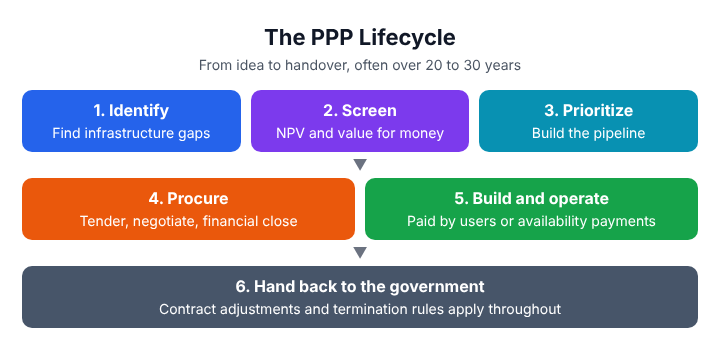
The PPP Project Lifecycle
Before any PPP is tendered, it goes through a structured selection process. The criteria differ by country, but the process follows three stages.
Stage 1: Identifying Potential Projects
A dedicated government PPP unit looks for infrastructure gaps where private participation could help. In many countries, private companies with relevant experience can also submit unsolicited proposals.
The government publishes its priorities, such as transport connectivity, energy access or housing. Public teams and private proponents then look for solutions that meet those priorities at the lowest public cost. This stage is deliberately broad; its job is to generate as many viable proposals as possible.
Stage 2: Screening
Screening imposes rigor. Each proposal is tested against two main questions:
- Does the project have a positive net present value for society?
- Does the PPP route give better value for money than conventional public procurement?
If a project can be delivered efficiently through standard public means, there is no reason to share returns with a private partner.
| Screening Parameter | What It Tests |
|---|---|
| Market demand | Is there enough user demand or social need to justify the project? |
| Private sector capability | Does the private partner bring skills or efficiency the government cannot match? |
| Risk allocation feasibility | Can project risks be shared between the parties in a sustainable way? |
| Financing viability | Can the project attract debt and equity on acceptable terms? |
Stage 3: Pipeline Prioritization
Projects that pass screening enter a pipeline, an ordered queue that the government works through as funds and capacity allow. Three factors usually drive priority:
- Probability of success: Projects likely to attract strong private funding need less public subsidy, freeing money for other projects.
- Competitive spillovers: Projects that make domestic businesses more competitive are ranked higher.
- Track record: Where private firms have delivered similar projects elsewhere, implementation risk is lower.
The government then issues requests for proposals, and procurement (tendering, negotiation and financial close) begins.
The Economics of PPPs
Sound PPP design rests on economic principles, not political convenience.
- Incentive alignment: Private partners must be motivated at every stage, from bidding through construction, operation and handover. Concession models link the operator’s income to the asset’s performance. When political pressure stops an operator from collecting agreed tolls, as has happened in several markets, the incentive collapses and future private investment dries up.
- Risk and return calibration: Each risk should go to the party best able to manage it, and be priced honestly at the outset. Contracts skewed too far either way become unstable.
- Moral hazard: When governments rescue failing PPP partners through soft loans or bailouts, they reward imprudent bidders and penalize those who bid conservatively. Rescues should be rare and governed by clear rules.
- Demand and supply balance: Investment goes wrong when it is not based on realistic demand forecasts. Empty special economic zones and unsold public housing tie up capital unproductively.
- Resource trade-offs: The public money that could fund an airport could instead fund rural clinics or schools. PPPs ease this tension by attracting private capital to commercially viable assets. But PPPs that rely on large guarantees or hidden subsidies simply consume public money through the back door.
Payment Mechanisms
How the private partner is paid is one of the most important design decisions. It decides who bears demand risk and how incentives work.
- User charges: Users pay tolls, airport charges or usage fees, and the private party keeps the revenue. Because PPP assets are usually monopolies, prices follow a pre-agreed formula, often overseen by a regulator.
- Revenue-based payments with a ceiling: These work like user charges, but revenue above a set ceiling goes to the government, or the concession ends early once a target revenue is reached, as in Chile’s road auctions. This answers the criticism that operators bid on pessimistic traffic forecasts and then profit when traffic is higher.
- Availability payments: The government pays a fixed periodic amount if the asset is available and meets service standards, regardless of how many people use it. The private party bears construction and performance risk; the government bears demand risk. This model is common for hospitals, schools and many roads.
- Tax-funded payments: Payments come from a levy outside the project, for example a charge on conventional energy that funds renewable energy contracts. This suits new technologies with unpredictable revenues.
| Mechanism | How It Works | Who Bears Demand Risk | Best Suited For |
|---|---|---|---|
| User charges | Users pay directly | Private party | Busy roads, airports, bridges |
| Revenue with ceiling | User charges, with excess shared or term shortened | Shared | Projects with uncertain but estimable revenue |
| Availability payments | Government pays for available, compliant service | Government | Hospitals, schools, low-traffic roads |
| Tax-funded payments | Funded by levies on alternatives | Taxpayers or consumers | New sectors with unpredictable revenues |
Choosing the wrong mechanism weakens the whole project and is far harder to fix mid-contract than at financial close.
Example: India’s Hybrid Annuity Model
India’s Hybrid Annuity Model (HAM), widely used for national highways, mixes government funding with availability-style payments.
- During construction: The government pays 40% of the project cost in five installments linked to construction milestones.
- The remaining 60%: The private developer raises it through its own equity and bank loans.
- During operation: The government repays that 60% in half-yearly annuities over the operating period, with interest on the outstanding balance, and also pays for operation and maintenance.
- Tolls: The government, not the developer, collects the tolls, so it bears the traffic risk.
HAM was introduced in 2016 after many toll-based road projects stalled, because developers had been reluctant to take on both large upfront investment and full traffic risk.
Contract Adjustment Mechanisms
PPP contracts last decades, and conditions will change. Good contracts include clear ways to restore balance:
- Financial equilibrium: Many PPP laws allow limited, pre-agreed adjustments when events outside the operator’s control, such as force majeure or government action, materially change the project’s economics.
- Changing service requirements: Contracts should say how changes to service standards are requested, who pays, and when a change needs formal renegotiation.
- Tariff adjustments: User charges must rise over time. Simple indexation to consumer prices may not keep up with actual costs; formulas linked to several cost drivers protect both sides better, though they are harder to administer.
- Refinancing: Once construction ends and risk falls, the project company can often replace expensive construction debt with cheaper long-term debt. Good contracts specify how the refinancing gain is shared between the project company and the government.
Early Termination
Early termination is costly for everyone and is a last resort. Contracts usually cover four scenarios.
- Termination for convenience: The government ends the contract because of a policy change, though no one has defaulted. It must usually compensate the private party for outstanding debt, invested equity and a reasonable return, so that this is never a cheap exit.
- Default by the public party: If the government fails to pay or meet its obligations, the private party can stop work and claim termination compensation, typically covering debt, equity and lost returns, based on an independent valuation.
- Default by the private party: This is the most common case, usually after repeated failure to meet deadlines or standards. The government should investigate the cause, issue warnings, allow a cure period, and only then terminate and levy penalties. Lenders usually have “step-in” rights to replace the operator first. These rights are set out in a direct agreement signed by the government authority, the project company and the senior lenders. Finding a replacement mid-project is difficult, so premature termination carries its own risks.
- Force majeure: Natural disasters, pandemics or other extraordinary events make the project impossible. Neither side is at fault. Compensation commonly covers outstanding debt and invested equity, without profit, so that the loss is shared.
Should the Government Take an Equity Stake?
Every infrastructure project needs equity investors who take the entrepreneurial risk. Usually these are experienced private firms, but governments sometimes take a stake themselves. The arguments run both ways.
| Argument For a Government Stake | Counter-Argument |
|---|---|
| Sharing the upside: The government takes much of the risk, so it should share in the profits. | Profits are uncertain, and private partners earn them because they control operations. A competitive lease or concession fee may capture value more reliably. |
| Control of strategic sectors: A stake gives insight into the company and influence over pricing. | Governance rules usually protect private shareholders from political decisions. Strong independent regulation may control pricing better than a board seat. |
| Reducing pressure on banks: Banks fund long-term projects with short-term deposits, creating a mismatch and crowding out other borrowers. | Incentives for long-term investors (pension funds, insurers, bond markets) may solve this more cheaply than government equity. |
| Signaling commitment: A government stake reassures private investors that the state will not change the rules. | It can create conflicts of interest when the government is also the regulator. |
In practice, government stakes are common in some sectors, such as airports and urban transit, often through state-owned enterprises. They work best when the government’s role as shareholder is clearly separated from its role as regulator.
Governance and Structural Challenges
- Transparency gaps: When contract terms are hidden, citizens cannot judge value for money. Disclosure and independent audits are essential.
- Political risk: PPPs span several election cycles. Strong legal frameworks and credible dispute resolution protect investor confidence.
- Risk allocation discipline: Governments are tempted either to push too much risk onto private parties or to give them too much protection. Risk allocation should follow economic logic, not negotiating power.
Frequently Asked Questions
What is the difference between a PPP and privatization?
In privatization, the government permanently transfers ownership to a private company. In most PPPs, the government keeps ownership of the asset and regains full control when the contract ends.
What is an SPV and why is it used?
A special purpose vehicle is a separate company created only for the project. It ring-fences the project’s assets and debts from its parent companies and protects lenders.
What happens if a project earns far more than projected?
It depends on the contract. Under a pure user-charge model, the private partner keeps the extra profit. Under a revenue-ceiling model, the excess goes to the government or the concession ends early.
How are lenders treated if a project ends early?
The contract sets this out. When the private party defaults, some contracts make lenders accept a partial loss (a “haircut”), so that they keep an incentive to monitor the project rather than rely on termination payments.
Can PPP contracts be renegotiated?
Yes, through the adjustment mechanisms written into the contract. Renegotiation outside those mechanisms, especially soon after the contract is signed, is a warning sign of poor design or opportunistic bidding.