
Capital budgeting involves three fundamental steps: identifying cash flows, choosing a discount rate that reflects the time value of money and risk, and discounting those cash flows. The process is complicated because all of these numbers are uncertain. Estimates are at best approximations, and small changes can substantially alter a project’s value.
Estimating cash flows correctly is also counterintuitive at times, mainly because the approach is often the opposite of what you would do in accounting.
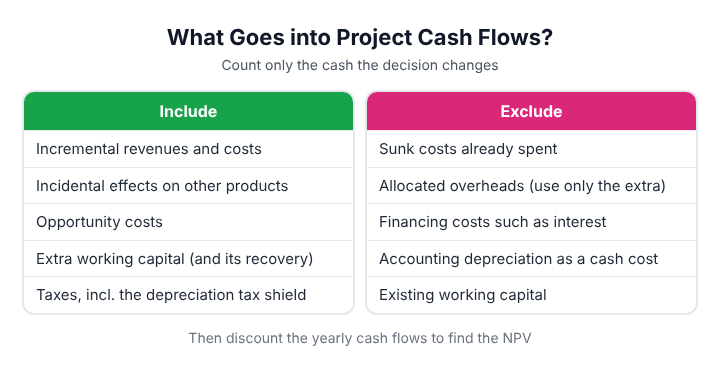
This guide walks through the full set of adjustments and concepts involved: converting accounting profits into cash flows, incremental cash flows and incidental effects, opportunity costs, incremental working capital, sunk costs, allocated overheads and taxes.
It then puts them together in a worked example, and ends with a look at how creative financial managers can add value by changing when and how a project is carried out.
Deriving Cash Flows from Accounting Profits
Capital budgeting depends entirely on cash flows rather than accounting profits. Analysts usually start from financial statements that show accounting profits, which requires two key adjustments:
- Timing differences: Accountants recognize income when it is earned, while cash flow reflects when money is actually received or paid. The numbers must be adjusted accordingly.
- Expenses vs. assets: Accountants distinguish between expenses and the creation of assets, spreading the cost of an asset over its life through depreciation. Cash flow analysis records the full cash outflow when the money is actually spent. Depreciation itself is not a cash flow, though it does affect taxes, as explained below.
Only Incremental Cash Flows Matter
Each project should be evaluated separately, considering only the incremental cash flows that result from that specific decision.
For example, suppose a company owns a property that it rents out for $10,000 a year, and it is thinking of opening a restaurant there instead. If the restaurant would generate $25,000 a year in cash, the incremental cash flow is only $15,000, because the company gives up $10,000 of rent.
The analysis should always compare the firm’s cash flows with and without the investment, focusing only on the additional dollars the new project generates.
Incidental Effects
Projects rarely operate in isolation. If introducing a new car model reduces sales of an existing model by $12,000, that $12,000 is an incidental cost and must be subtracted from the new model’s cash inflows.
Incidental effects can be positive too. A new product might increase sales of related products, and those extra sales belong in the analysis.
Opportunity Costs
Opportunity costs are notional or implicit costs. The money never actually leaves your pocket, but the cost is real in economic terms. An opportunity cost is the value of the next-best alternative given up when resources are used for a project.
Consider a scarce resource like your time. If reading and watching a movie are the only two things you could do with an evening, then watching the movie means giving up reading. Reading is the opportunity cost of the movie, and vice versa.
Similarly, when a firm invests money in Project A, it is not investing that money in Project B. The returns Project B would have generated must be taken into account. The goal of capital budgeting is to make the best choice among competing alternatives, so the foregone alternative has to be factored in. Accounting ignores this cost, but corporate finance does not.
Estimating opportunity cost can be difficult. If there is a ready market for the asset in question, such as land or a building, market prices or rents can be used. If not, the value may need to be estimated, sometimes with the help of a professional appraiser.
One more point: the opportunity cost of Project A can never be greater than the value of Project A itself. If it were, the other project should simply be chosen instead.
Incremental Working Capital
Just as with capital expenditure, only the extra working capital needed because of the new project should be considered. Existing working capital is excluded, since it is unaffected whether or not the project goes ahead.
A new project often needs money tied up in inventory and in credit given to customers, offset partly by credit received from suppliers. This investment is a cash outflow at the start of the project.
Working capital is usually rolled over from one period to the next rather than requiring fresh cash each time. At the end of the project, the working capital is released, and this recovery is added back as a cash inflow when calculating net present value (NPV). This is another counterintuitive step for anyone used to accounting.
Sunk Costs
Sunk costs are expenses that happened in the past and will not be affected by the current decision. Defining a sunk cost simply as “past spending” is incomplete; a cost is only truly sunk if no current or future decision can change or recover it.
Consider a firm that has already spent $1 million on a project that has not yet produced any positive cash flows. The company now has to decide whether to invest further or pursue a new project instead.
The $1 million already spent has nothing to do with the choice at hand. The decision must be based solely on the NPV of the money that would be spent from now on. The old $1 million is gone either way, so it is irrelevant and should be ignored.
Allocated Overhead Costs
Overheads are costs that cannot be assigned directly to any single activity, such as head office rent or senior management salaries. Accountants spread them across departments and projects using a formula, such as labor hours. The trouble is that these allocated costs may not be the right numbers for cash flow analysis.
For example, say a company has three departments with total overheads of $100, allocated by labor hours. Departments A and B each use 40 hours, and C uses 20 hours, so A and B are each allocated $40 and C $20.
Now a fourth department, D, is added. It brings $20 of extra overhead, raising the total to $120, and uses 50 labor hours. With 150 hours in total, each hour now carries $0.80 of overhead. A and B are allocated $32 each, C $16 and D $40.
Department D is allocated $40 of overhead, even though it only added $20 in real costs. Since cash flow analysis is about incremental costs, the $20, not the $40, should be used.
Tax Considerations and the Depreciation Tax Shield
Taxes are a real cash outflow and must be included. Two points matter most:
- Use after-tax cash flows: Extra profit from a project increases the company’s tax bill, so cash flows should be measured after tax.
- Depreciation saves tax: Depreciation is not a cash payment, but it reduces taxable profit and therefore reduces the tax the company pays. This saving, called the depreciation tax shield, is a genuine cash benefit.
A common shortcut is:
Here, after-tax operating profit means earnings before interest and taxes (EBIT) multiplied by one minus the tax rate, often called NOPAT. It is not the same as net income, which is calculated after interest.
Financing costs, such as interest payments, are usually not deducted from project cash flows. They are captured in the discount rate instead, so deducting them as well would count them twice.
Putting It Together: A Step-by-Step Method
- List the initial investment, including equipment, installation and extra working capital.
- Estimate the extra revenues and costs the project will bring each year, including incidental effects.
- Subtract any opportunity costs, such as income given up from using an existing asset.
- Calculate taxes on the extra profit, remembering the depreciation tax shield.
- Add back the recovery of working capital, and any sale value of equipment, at the end.
- Leave out sunk costs, allocated overheads and financing costs.
- Discount the yearly cash flows to find the NPV.
A Worked Example
A company is considering a three-year project. It needs a $90,000 machine, depreciated evenly over three years ($30,000 a year), and $20,000 of extra working capital. The project will bring in $90,000 a year in revenue, with cash costs of $40,000. The tax rate is 25%.
The project will use factory space the company could otherwise rent out for $4,000 a year (an opportunity cost of $3,000 a year after tax). The company has already spent $5,000 on a market study. Its discount rate is 10%.
| Item | Year 0 | Year 1 | Year 2 | Year 3 |
|---|---|---|---|---|
| Machine | -90,000 | |||
| Working capital | -20,000 | +20,000 | ||
| Revenue minus cash costs | 50,000 | 50,000 | 50,000 | |
| Tax (25% of 50,000 minus 30,000 depreciation) | -5,000 | -5,000 | -5,000 | |
| Rent given up, after tax | -3,000 | -3,000 | -3,000 | |
| Net cash flow | -110,000 | 42,000 | 42,000 | 62,000 |
Discounting at 10% gives an NPV of $9,474 (about $9,500), so the project is worth doing.
Notice what was left out. The $5,000 market study is a sunk cost, so it does not appear. If the analyst had forgotten the $3,000 a year of rent given up, the NPV would have been overstated by about $7,500, which is a reminder of how much opportunity costs can matter.
Practical Guide: Calculating the Depreciation Tax Shield
The depreciation tax shield is one of the most frequently mishandled inputs in capital budgeting. In the worked example above, it is already built into the tax line: depreciation of $30,000 a year cut the tax bill by $7,500 a year. Here is how to calculate it step by step.
- Find the depreciable amount: Start with the full cost of buying and installing the asset. Exclude land, which does not depreciate, and deduct any salvage value if the tax rules require it.
- Apply the tax depreciation method: Work out each year’s depreciation using the method allowed for tax purposes, such as straight-line or an accelerated schedule (for example, MACRS in the US).
- Multiply by the tax rate:
Depreciation tax shield = Depreciation expense × Tax rate - Build it into operating cash flow: There are two equivalent ways to calculate OCF:
- Top-down approach: OCF = (Revenue − Cash expenses − Depreciation) × (1 − Tax rate) + Depreciation
- Tax-shield approach: OCF = (Revenue − Cash expenses) × (1 − Tax rate) + (Depreciation × Tax rate)
Quick check using the worked example: Revenue minus cash costs is $50,000, depreciation is $30,000 and the tax rate is 25%.
- Top-down: ($50,000 − $30,000) × 0.75 + $30,000 = $45,000
- Tax-shield: $50,000 × 0.75 + ($30,000 × 0.25) = $37,500 + $7,500 = $45,000
Both give $45,000 before the $3,000 of rent given up, which is exactly the $42,000 net cash flow shown for Years 1 and 2. Depreciation itself is a non-cash entry, but it shields $30,000 of profit from tax and keeps $7,500 of real cash in the business each year.
Summary of the Key Rules
| Concept | Financial rule | Practical example |
|---|---|---|
| Incremental cash flows | Count only cash flows caused by the project | New restaurant revenue minus rent that would have been earned anyway |
| Incidental effects | Include effects on the company’s other products | A new car model taking sales from an existing model |
| Opportunity cost | Include the value of the next-best alternative given up | Rent foregone on factory space used by the project |
| Incremental working capital | Count only new working capital; add it back at the end | $20,000 invested in Year 0 and recovered in Year 3 |
| Sunk costs | Ignore past spending unaffected by the decision | A $5,000 market study already paid for |
| Allocated overheads | Use the incremental overhead, not the allocated share | A new department’s real $20 cost vs. its $40 allocated share |
| Taxes | Use after-tax cash flows; include the depreciation tax shield | Depreciation lowers the tax bill by $7,500 a year in the example |
Thinking Creatively: Timing and Phasing
The steps above can make capital budgeting look like a fixed procedure. In reality, good financial managers find creative ways to make projects more valuable, often by changing when or how a project is carried out. Economists call these choices “real options.”
The Option to Wait
The NPV rule says that a project with a positive NPV is worth doing. It does not say the project must be started today.
Imagine a company planning to build an office block. Its analysis shows a positive NPV. But it then learns that the government may soon declare a nearby area a tax-free business zone and build a new metro line to the city center. If that information is credible, property values, and therefore the project’s value, could rise sharply. Waiting a year or two might make a good project a great one.
Every project therefore has at least two options: start now or start later. Some projects with a negative NPV today may become attractive in a few years. Part of the financial manager’s job is to look ahead for information that could change a project’s value.
The Option to Phase or Stage
Large projects, such as re-engineering a whole factory, are often treated as all-or-nothing decisions. Creative managers ask whether the project could be split into stages.
Carrying out 25% of a project each year for four years, for example, may produce a higher NPV than doing everything at once. Staging lets the company learn from the first phase, spread its spending and stop if conditions turn against it.
The Option to Expand or Abandon
Projects can also be designed so that the company can expand them if they succeed, or abandon them and sell the assets if they fail. This flexibility has value that a simple NPV calculation does not capture.
The lesson is that the aim is always to maximize value, and that the obvious way of carrying out a project is not always the best one.
Frequently Asked Questions
Why does capital budgeting use cash flows instead of accounting profits?
Because accounting profits follow rules about when income is recognized and how assets are depreciated, which do not reflect when cash actually moves. Capital budgeting needs the real cash impact of a decision.
Why are sunk costs ignored in capital budgeting?
Money already spent cannot be recovered or changed by today’s decision, so it has no bearing on whether a new or continued investment makes sense. Only future costs and benefits matter.
What is the difference between allocated and incremental overhead?
Allocated overhead is a share of total company overhead assigned to a department using a formula. Incremental overhead is the actual extra overhead a new project causes. Only the incremental figure belongs in cash flow analysis.
Why is working capital added back at the end of a project?
Money tied up in inventory and customer credit at the start is usually recovered when the project winds down, so it is treated as a cash inflow at that point.
Should interest payments be included in project cash flows?
Usually not. The cost of financing is reflected in the discount rate, so deducting interest from the cash flows as well would count it twice.
What does it mean to have an option to wait?
It means a company can delay a project to gather more information. If waiting is likely to increase the project’s value, it may be better to start later, even if the project already has a positive NPV.