
The money market is where governments, banks and companies borrow and lend for short periods, from overnight to a year. One of its most important parts is the commercial paper (CP) market, through which large companies raise short-term funds directly from investors.
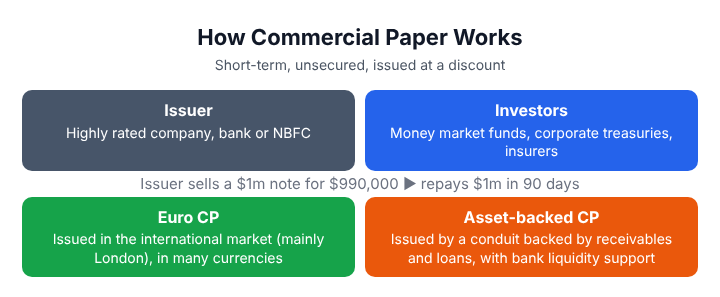
Commercial paper is simple in concept. A company with a strong credit rating issues a short-term promissory note, and investors such as money market funds buy it. The company gets cheap short-term funding; investors get a safe place to park cash for a few weeks.
The market is large. In the United States alone, more than $1 trillion of commercial paper is typically outstanding. In India, CP is a key source of short-term funding for companies and non-bank finance companies.
This article explains how commercial paper works, who issues and buys it, why companies use it, and how two important variants, Euro commercial paper and asset-backed commercial paper, differ from standard CP.
What is Commercial Paper?
Commercial paper is an unsecured, short-term promissory note issued by companies with strong credit ratings. Its main features are:
- Unsecured: It is backed only by the issuer’s creditworthiness, not by collateral (except asset-backed CP, discussed below).
- Short maturity: In the US, CP matures in at most 270 days, which exempts it from SEC registration under the Securities Act. Most US CP matures within about 30 days. In India, CP can be issued for 7 days to one year.
- Issued at a discount: CP usually pays no coupon. It is sold below face value and repaid at face value; the difference is the investor’s return.
- Large denominations: In the US, CP is usually sold in units of $100,000 or more. In India, under the Reserve Bank of India’s directions on commercial paper, the minimum is ₹5 lakh, and larger amounts must be in multiples of ₹5 lakh. As a result, retail investors usually invest in CP indirectly, through money market or liquid funds.
- Rated: Investors and regulators rely on credit ratings. In India, CP must be rated by a registered credit rating agency.
How Discount Pricing Works
A company issues CP with a face value of $1,000,000, maturing in 90 days, at a price of $990,000.
- Investor’s return: $1,000,000 − $990,000 = $10,000
- Return over 90 days: $10,000 ÷ $990,000 ≈ 1.01%
- Annualized yield (365-day basis): 1.01% × 365 ÷ 90 ≈ 4.1%. This is the investment yield, also called the bond equivalent yield.
Two Ways to Quote the Yield
Commercial paper, like Treasury bills, is often quoted as a bank discount yield, which looks lower than the return an investor actually earns.
- Bank discount yield divides the discount by the face value and uses a 360-day year:
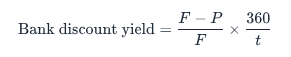
- Bond equivalent yield divides the discount by the price actually paid and uses a 365-day year:
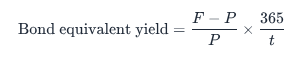
In the example above, the bank discount yield is $10,000 ÷ $1,000,000 × 360 ÷ 90 = 4.00%, while the bond equivalent yield is about 4.1%. The gap widens as rates rise. To compare commercial paper fairly with Treasury bonds or bank deposits, convert every quote to the bond equivalent yield.
Who Issues Commercial Paper?
Issuers are mainly private corporations, divided into:
- Financial companies: Banks, finance companies and, in India, non-bank financial companies (NBFCs). They are the largest issuers and use CP to fund their lending.
- Non-financial companies: Large industrial and consumer companies that use CP to fund working capital, such as inventories and receivables.
Who Buys Commercial Paper?
- Money market funds: The largest investors in most markets.
- Corporate treasuries: Blue-chip companies with surplus cash.
- Insurance companies and pension funds: For the short-term part of their portfolios.
- Government bodies: State and local governments and state-owned entities with surplus funds.
- Banks: In some markets, banks hold CP as a short-term investment.
Why Do Companies Issue Commercial Paper?
- Low cost: For highly rated issuers, CP is usually cheaper than bank loans or overdrafts.
- Flexibility: Companies can issue exactly the amount they need, for the period they need it.
- Rolling over: Issuers often repay maturing CP by issuing new CP. This lets them use the funds for longer periods, although it creates rollover risk if the market closes.
- Less paperwork: Issuing CP is much quicker and simpler than issuing bonds, because it is sold mainly to professional investors and has lighter disclosure requirements.
- Dealer networks: Large issuers sell CP through dealers, often daily, giving them ready access to investors.
The main risk for issuers is that the market can close to them suddenly. After a negative credit event, investors may refuse to roll over their CP, forcing the issuer to draw on bank credit lines. For this reason, most CP issuers keep backup lines of credit with banks. In 2008 and again in March 2020, CP markets came under such stress that the US Federal Reserve set up a Commercial Paper Funding Facility to buy CP directly.
| Feature | United States | India |
|---|---|---|
| Regulator | SEC exemption rules; Federal Reserve oversight of banks | Reserve Bank of India |
| Maturity | Up to 270 days (most within about 30 days) | 7 days to 1 year |
| Minimum size | Usually $100,000 | ₹5 lakh |
| Rating | Market practice; most issuers top-rated | Mandatory credit rating |
| Main issuers | Banks, finance companies, large corporations | Companies, NBFCs, financial institutions |
| Main investors | Money market funds | Mutual funds (especially liquid funds), banks |
Euro Commercial Paper (ECP)
Euro commercial paper is commercial paper issued in the international market, outside the domestic market of the currency it is denominated in. The “Euro” refers to the offshore (Euromarket) nature of the paper, not to the euro currency. ECP is arranged mainly in London and can be issued in US dollars, euros, sterling and other currencies.
Its main features compared with US CP:
- Investor base: Central banks, supranational institutions and multinational treasuries are important investors, alongside money market funds.
- Issuers and credit quality: ECP includes more unrated and lower-rated issuers than the US market, which is dominated by top-rated names. Investors may therefore earn slightly higher yields.
- Currency flexibility: Multinationals can borrow in the currency they need for their operations, avoiding the need to borrow in one currency and convert.
- Maturity: ECP tends to have longer average maturities than US CP.
- Settlement: US CP usually settles on the same day. ECP usually settles two business days after the trade, through Euroclear and Clearstream.
Asset-Backed Commercial Paper (ABCP)
Asset-backed commercial paper is CP backed by a pool of assets rather than by a single company’s credit.
- A sponsor, usually a bank, sets up a special purpose vehicle called a conduit, which is “bankruptcy remote” from the sponsor.
- The conduit buys assets, such as trade receivables, car loans, credit card balances or student loans, from one or several sellers.
- It funds these purchases by issuing short-term ABCP to investors.
- Credit enhancement, such as over-collateralization or reserves, protects investors against losses on the assets.
- Because the assets usually last longer than the ABCP, the conduit relies on rolling over its paper. A liquidity facility from the sponsor bank promises to provide cash if the paper cannot be rolled over.
Single-seller conduits buy assets from one company. Multi-seller conduits buy from many, which improves diversification.
ABCP began in the 1980s and grew rapidly. In the US, outstanding ABCP peaked at about $1.2 trillion in 2007. When investors lost confidence in mortgage-related assets that summer, they refused to roll over ABCP, and the market collapsed. In Canada, about $32 billion of non-bank ABCP froze completely and had to be restructured. Today the market is smaller, and liquidity support rules are stricter.
| Feature | Standard CP | Euro CP | Asset-Backed CP |
|---|---|---|---|
| Backing | Issuer’s credit | Issuer’s credit | Pool of assets in a conduit |
| Market | Domestic (e.g., US, India) | International (mainly London) | Mainly US and Europe |
| Typical issuers | Highly rated companies, banks, NBFCs | Multinationals, banks, sovereign entities | Bank-sponsored conduits |
| Settlement | Usually same day in the US | Usually two days | Usually same day in the US |
| Key risk | Issuer default, rollover | Issuer default, currency | Asset quality, rollover, liquidity support |
Frequently Asked Questions
What is commercial paper in simple words?
It is a short-term, unsecured loan that large companies raise directly from investors by selling notes at a discount and repaying the full amount at maturity.
Why does US commercial paper mature within 270 days?
Because notes with a maturity of up to 270 days, used for current transactions, are exempt from SEC registration, making them cheaper and quicker to issue.
Can individuals invest in commercial paper?
Usually not directly, because of the large minimum amounts. Most individuals invest through money market or liquid mutual funds.
What is the difference between commercial paper and a certificate of deposit?
Commercial paper is issued by companies and is unsecured. A certificate of deposit is issued by a bank and is a deposit of that bank.